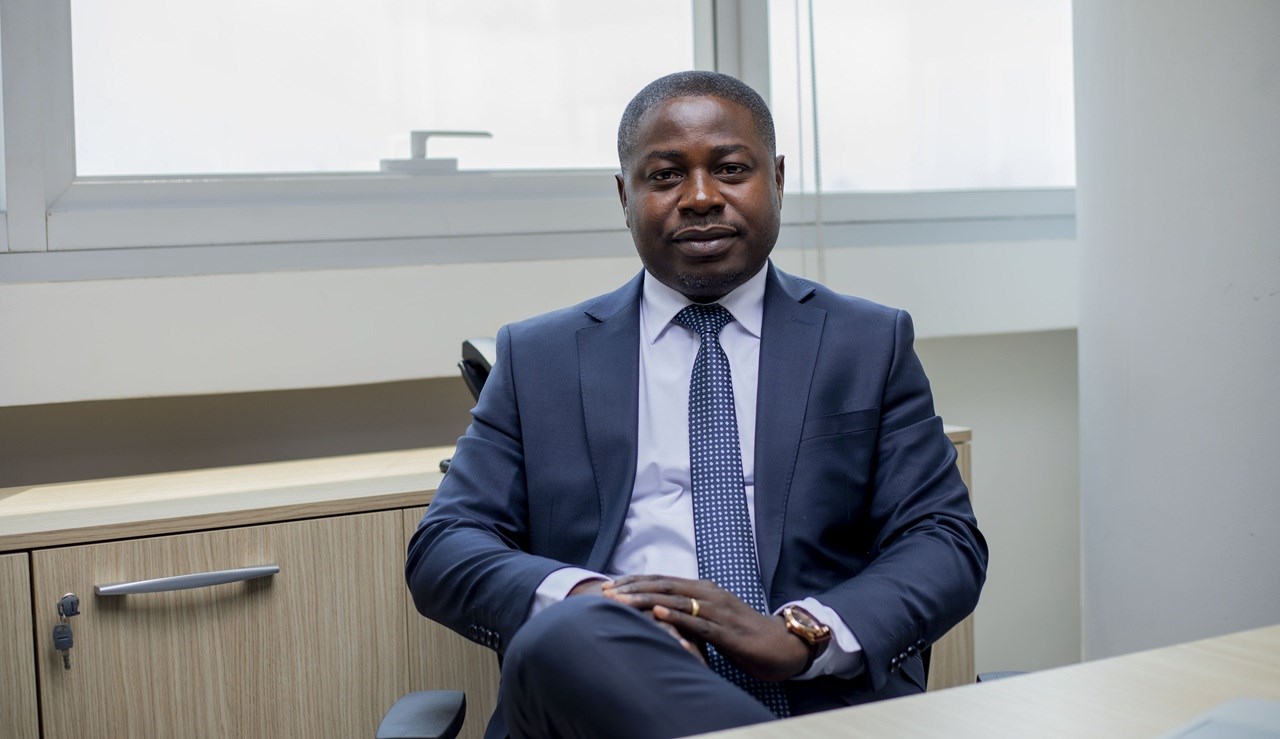
Didier Assemian, Head of Claims at GNA-CI: GNA-CI, the second-largest IARDT insurer in Côte d'Ivoire and the CIMA zone, officially launches " 0 dry" compensation in October 2026 at its Accelerated Claims Center (C.I.A.). Created in 2020 and dedicated to the rapid settlement of motor insurance claims, the facility is deployed at four sites in Abidjan, San-Pedro, and Bouaké.
Didier Assemian, the company's Head of Claims, details its operations, scope, and commitments. What is the Accelerated Claims Center, concretely?
An insurer is judged on the day of the loss. The rest of the time, it sells a promise.
The C.I.A. is our response to that day: a location, a team, and a procedure brought together to settle a motor insurance claim without requiring the client to return. Reporting, assessment, decision-making, and settlement occur in the same place.
We have eliminated the back-and-forth, because that is where time is lost. You are announcing " 0 dry" compensation.
What exactly does this figure measure? It measures the wait between file validation and payment.
Once the claim is validated, the settlement is delivered immediately, on-site. I specify this because the wording matters: we are not promising a file processed in zero seconds.
We are promising that a validated file no longer waits. The C.I.A. already existed.
What is changing? Since 2020, the C.I.A. had been settling motor insurance claims in less than four hours.
We analyzed the sequence of those four hours, step by step, and removed what did not serve the client. Two developments made the difference: the payment decision is now taken in each center, as close as possible to the policyholder; and the settlement can be paid via mobile money.
Does paying quickly mean less control? No, and this is the point I care about most.
The controls are the same; they are performed earlier and in the same location. Documentation, expert assessment, verification of coverage: everything is gathered before the decision is made.
An incomplete file, or one requiring investigation, follows the standard process. Speed comes from organization, not from relaxed vigilance or haste.
Which claims are affected? Three situations allow access to the C.I.A.
The first: the policyholder is not responsible for the accident and has subscribed to the Recourse Advance coverage. We compensate them, then we pursue the recourse ourselves.
The second: the policyholder is covered under All-Risks Damage. The third: the accident involves two GNA-CI policyholders, even in simple recourse.
A practical condition is added: the vehicle must be able to be presented at the center; towed vehicles are not handled there. Bodily injury or complex files follow their own specific process and timelines; we do not claim otherwise.
Why San-Pedro and Bouaké, in addition to Abidjan? Because a vehicle awaiting repair costs just as much in San-Pedro as it does in Marcory.
For a carrier, a merchant, or a PME, every day of waiting is a day without revenue. San-Pedro lives off its port, Bouaké is a road junction: these are cities where the vehicle is a work tool.
Payment is decided there on-site, without going back up to Abidjan. What does this speed cost the company?
Less than one might think. A due claim is already provisioned: paying it sooner changes the date, not the amount.
Conversely, a long-running file generates follow-ups, complaints, and additional management costs. A client compensated without waiting has every reason to stay.
We treat the settlement turnaround time as a management indicator, not as an advertising argument. How will you measure that the facility is meeting its commitments?
By the stopwatch, file by file. Our benchmark is our own history: less than four hours yesterday, zero waiting after validation today.
A week after implementation, more than a dozen policyholders have been compensated on-site, without a waiting period. We present ourselves as the vitamin of insurance.
A vitamin is judged by its effects, not by its packaging. Published on 15/10/26 15:12 The Editorial Staff